

Growing a career and team in Christchurch: Penny Ineson’s leadership story
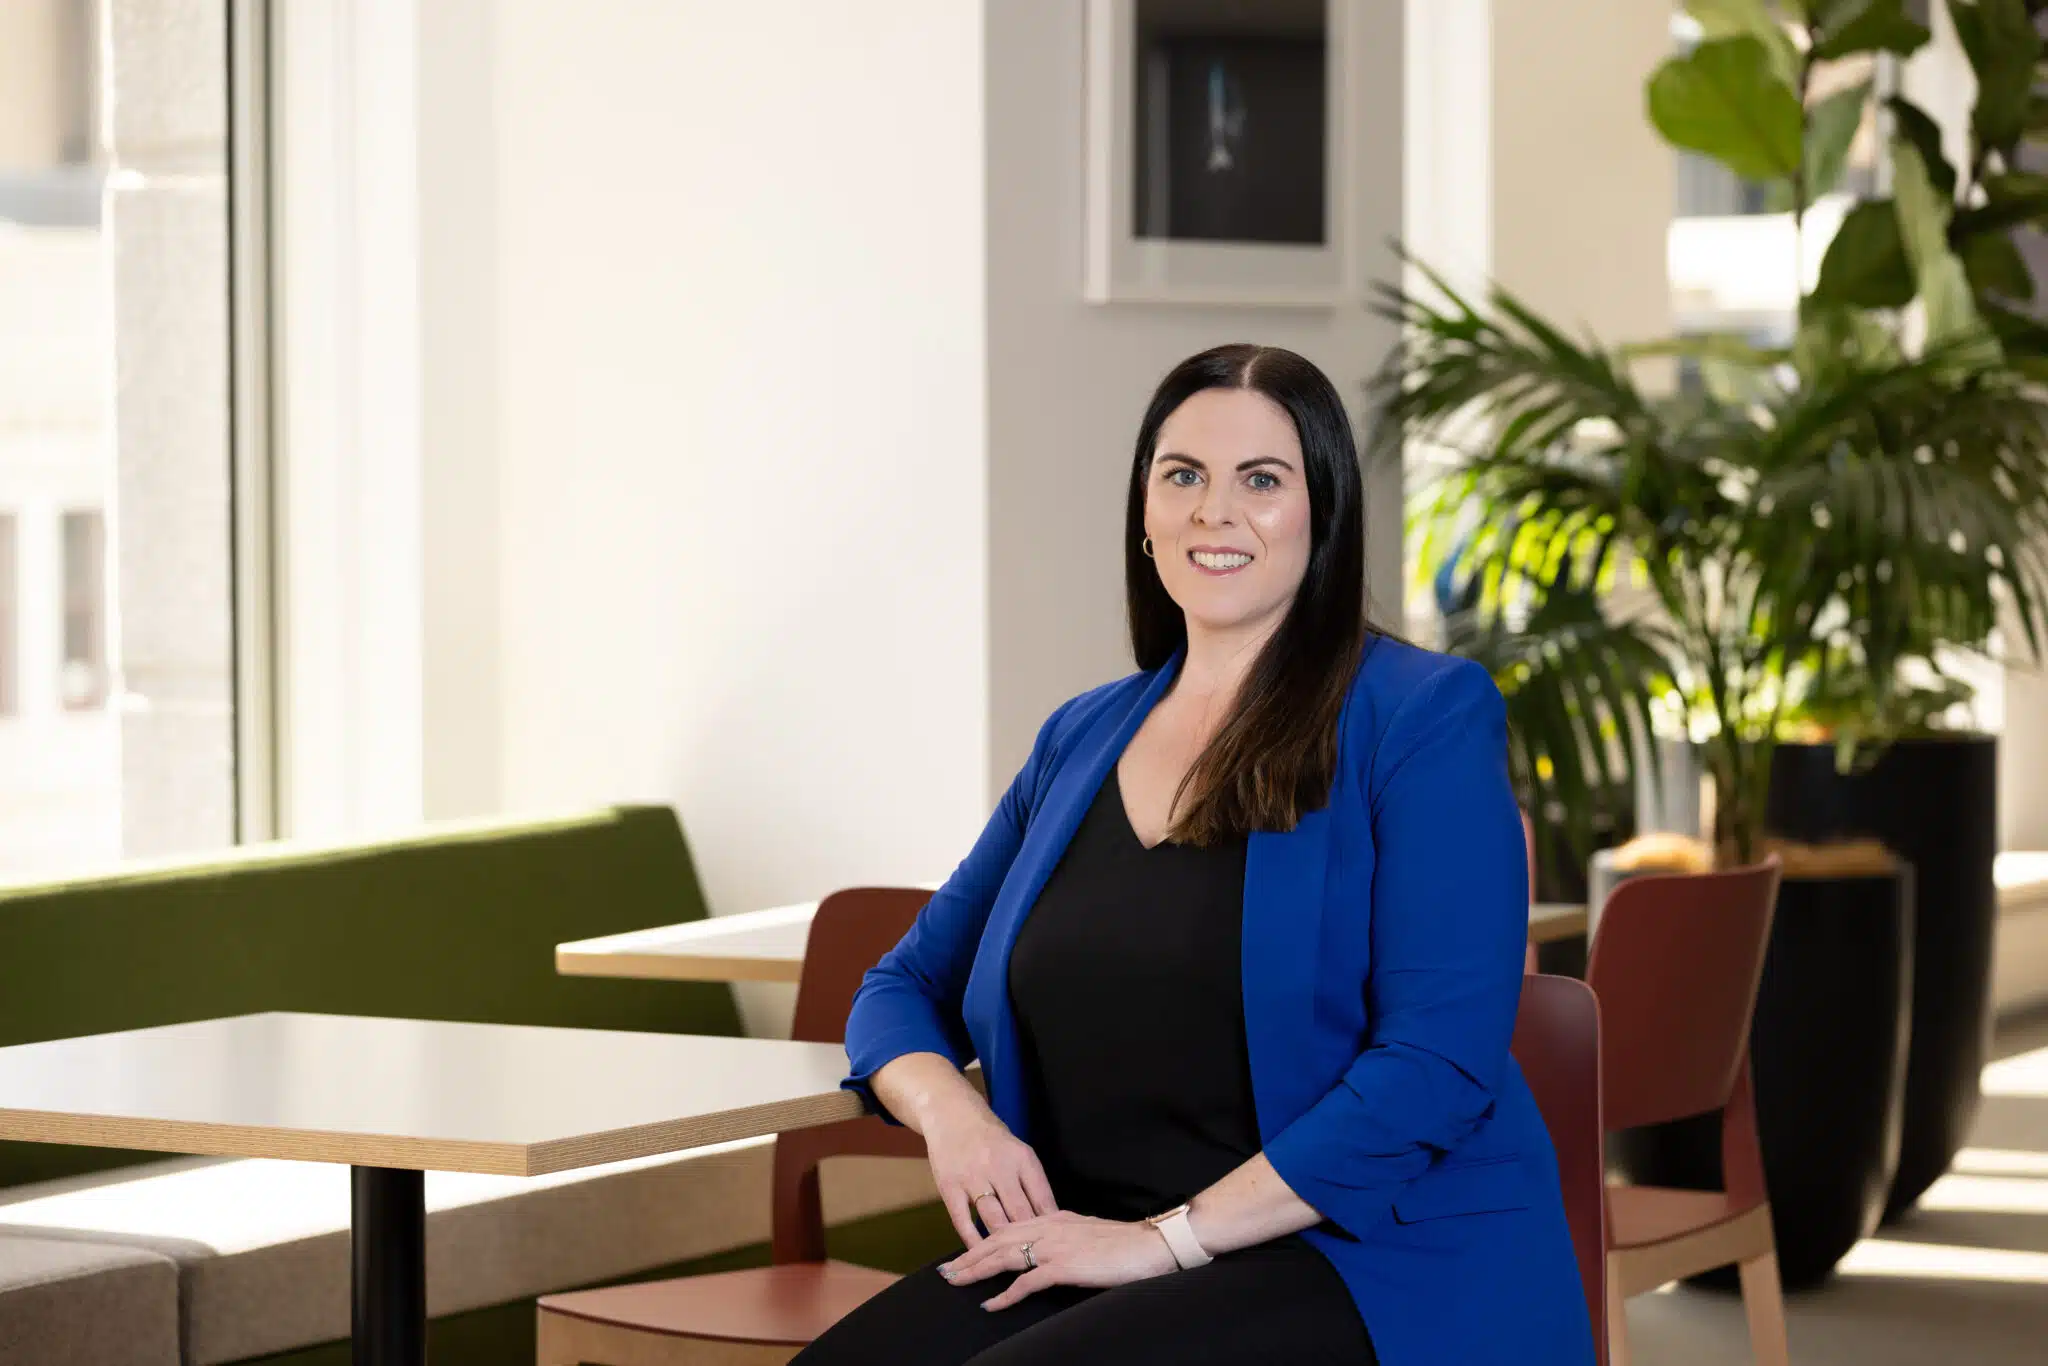
When Penny Ineson joined TMNZ 10 years ago, she had an ambitious 90-day plan that included starting a Christchurch office. A decade later, that plan has come to life. With a recent promotion to Head of Advisor Relationships – South Island, Penny now leads a team of four, aiming to ‘take the South Island by storm’ in tax payment solutions.
How are you feeling about your new leadership role?
I am so excited! It’s a little nerve-wracking because, while the investment is in the South Island, it’s also an investment in me. But I always feel valued and supported by TMNZ to work hard and do my job well. Throughout my promotions (Business Development Manager, Senior Client Relationship Manager, and Regional Manager), I’ve received ongoing support, great communication and connection with the wider team , and flexible working hours, which have allowed me to manage maternity leave, complete my Bachelor of Commerce in Accounting, and most recently, secure office space in Christchurch.
What’s the best thing about your job?
I love interacting with people; my clients are down-to-earth and genuine. I enjoy helping businesses with tax; it’s rewarding to hear how TMNZ supports them to grow or navigate tough times.
What does it mean to you to be a female leader in accounting?
It’s really special. I love networking with other female leaders in the industry. At TMNZ we have held a number of events where we acknowledge female leaders within the accounting and tax industries. I’ve witnessed more and more women rise in the industry, and now that’s me too, so I’m proud.
What does your promotion signal about TMNZ’s growth and success in the South Island?
From 2015 to 2021, I was the primary person managing accounts in the South Island. In 2022, I gained the support of Isabella Prichard (Customer Growth Manager,Auckland) to reach more clients. We work exceptionally well together and wouldn’t be where we are now without her ambition, enthusiasm, and drive.
While we have done well to spread the word about TMNZ’s provisional tax solutions across the South Island, there are still many people and businesses that don’t know how we can help them. Now, we have Harry Macgregor (Customer Success Manager,) and Lexie Weaver (Customer Success Consultant) on board in Christchurch.
TMNZ’s investment shows the faith they have in us and our ability to take the South Island by storm.
What did you take into account when hiring new team members?
It’s so important for our team to be able to relate to and care about people regardless of whether they’re paying $500 or $5,000,000. Tax can be a stressful topic for people, so we need staff who are compassionate as well as qualified.
Lexie, a science graduate from Victoria University, has empathy in spades and great problem-solving skills, and Harry, a Chartered Accountant, can walk into a room and start a conversation with anyone. It’s exciting to have a combination of knowledge and strong interpersonal skills.
How are you going to be supporting South Island businesses?
I have lots of ideas, but first and foremost, we’re going to be visiting the regions, listening to people’s pain points, and figuring out how we can help solve them.
We’ll be planning more events so we can get to know our clients in a more informal setting.
How do you maintain a good work/life balance?
My non-negotiable is a group fitness gym session in the morning. It’s the only time of day when my mind’s not racing; for 45 minutes, I’m just trying to survive the workout! I have amazing support from family and friends to help me maintain self-care amongst the chaos.
Please describe in three words how you’re feeling about the next 90 days.
Primed. Optimistic. Excited.
How can people get in touch?
I’d love to chat to anyone interested in learning how TMNZ can support their business (or their clients businesses) through our smart tax payment solutions. Please contact us here, and ask to speak with Penny.

From left: Penny Ineson—Head of Advisor Relationships South Island, Harry Macgregor—Customer Success Manager, Lexie Weaver—Customer Success Consultant

Enhancing financial flexibility for a healthcare services provider
The situation
The Finance Manager at a Healthcare Services business in Auckland, began working with TMNZ five years ago when the business experienced unexpected fluctuations in their retail operations. The business was looking for ways to maintain good cashflow while supporting the international group’s financial position.
The challenge
During the 2024-25 fiscal year, the Finance Manager was juggling many financial priorities, such as:
- meeting quarter-end, half-year, and year-end cashflow targets without incurring external debt
- maintaining tax compliance while optimising the balance sheet.
The solution
They chose to leverage TMNZ’s Tax Drawdown solution because:
- TMNZ provided more efficient and easier access to funds compared to other finance channels
- the solution helped optimise the balance sheet position, providing access to short term cash rather than long-term bank loans
- significant administrative costs were saved, including legal fees and bank covenant reporting requirements
- they could maintain their tax deposit date after repaying the drawdown.
The results
By using TMNZ’s services, the Healthcare business achieved:
- enhanced support for the international group’s financial position, contributing positively to the group’s risk profile
- the ability to temporarily access funds, which was highly valued by the international group’s treasury team
- improved cashflow management without incurring more costly third-party debt.
Your key takeaway
TMNZ’s solutions provide flexible and efficient tax management, aligning with business needs and supporting financial stability without the constraints of traditional finance channels.
For more on how our Tax Drawdown solutions can help your business, go here.
TMNZ: The ultimate cashflow flexibility tool for your business
In tough economic times, it can be hard for businesses to stay on top of cashflow and juggle their tax liabilities. For companies and sole traders dealing with fluctuating cashflow and provisional tax headaches, there’s an easier way to manage your obligations—tax pooling.
Did you know TMNZ’s tax pool can help you manage your tax by matching your cashflow forecasts with your provisional tax payments? And you can use tax pool deposits as an alternative funding source when cashflow is tight.
How we can help
TMNZ is an Inland Revenue (IR)-approved tax pooling provider, meaning you can use us to pay income tax on your behalf at a time that suits you. We offer greater flexibility over how and when you pay provisional tax.
First, you’ll need to think about your cashflow forecast. If you’re unsure how to put one together, read our cashflow management guide.
Once you’ve got your cashflow projection, we can work together to figure out the best time to pay your provisional tax. From there, all you need to do is tell us your tax amount owed, the date it is due, and how you would like to pay.
When your tax bill arrives, we’ll transfer the amount required to IR on your behalf as a time-stamped payment. IR will treat your tax as if it was paid on time, eliminating the risk of being charged interest or late payment fees. Simple.
A working capital solution
TMNZ’s payments to IR mean you can keep money in your business and use it at the times of the year you’ll need it most. You can top up your payments later into our tax pool at any time.
Tax pooling is a perfect solution for businesses worried about future cashflow and looming obligations. By partnering up with us, you’ll have total control over your tax bill, rather than working around IR’s strict deadlines.
With no more late fees and interest charges from IR to think about, you can get on with running your business. There will be no need to scrape together funds in the middle of holidays or quiet periods to meet IR’s deadlines.
TMNZ can also save you money by avoiding penalties and interest charges if you’ve missed or underpaid tax. We charge much lower interest rates than the penalties imposed by IR if you’re overdue.
We’re a line of credit
Another amazing TMNZ feature is that we can be a line of credit for your business.
If you’ve deposited funds into our tax pool but find yourself short on cash, you can withdraw that money whenever you want to use it as working capital.
If you’ve paid provisional tax into our pool, you’ll have access to a working capital facility up to the value of your deposit. This provides even more flexibility for you and your team to get through a cash crunch and stay on top of debt management.
We can offer much cheaper interest rates than bank loans, overdrafts, or unsecured loans, meaning money withdrawn from our pool is better for you and your business, putting you in a stronger position at the end of the year.
Ready to learn more about the benefits of tax pooling?
Download our guide to Better Cashflow Management for top tips on managing cashflow throughout the financial year.
If you’re ready to take control of your tax and gain access to a valuable line of credit for your business, find out more at by reading our Tax Pooling 101 page to learn more about the full range of benefits of being in our pool.
Then talk to your tax adviser about TMNZ tax pooling to take away your tax management worries.
The 7 May solution
We’re excited to share with you: Tax pooling – The 7 May solution. Discover how tax pooling makes 7 May easier for your clients by reducing pressure and minimising risk. We’ll cover the latest market insights and tax pooling best practices, with real-world examples that show exactly how it works.
What you’ll learn
- fresh market insights
- how to strengthen your clients’ tax approach without straining cashflow
- tips for staying ahead of your clients’ tax needs for 2025-2026
- tax pooling benefits in action through real examples
- Q&A
Who this is for
This webinar is perfect for tax agents and accountants in public practice.
This content is for general information purposes only and should not be used as a substitute for consultation with our team of specialists.
The interest rates mentioned in our webinars were accurate at the time of original recording. Please note that IRD interest rates change over time. Always refer to current official IRD rates for the most up-to-date information.
Book a tax pooling overview for your business
Is tax pooling the right solution for you? Every business we work with has different needs. Book an overview with one of our tax pooling specialists to find out how we can support you.
Utilising future tax to create working capital in the real estate industry
Working scenario: Bay Vista Real Estate
The situation
Emma runs a real estate agency in Auckland with 12 agents. The business experiences significant income fluctuations, with summer months (December-March) typically generating 60% of annual revenue.
The challenge
During the 2024-25 tax year, Bay Vista faced:
- peak income during the summer months
- large commission payments to agents in December/ January
- lower winter income but consistent overhead costs
- two of their provisional tax payments due during quieter months
- a preference for flexibility to withdraw funds if new opportunities arose.
The solution
Emma chose a TMNZ solution which allowed her to:
- delay payment of provisional tax due in August until a time when the business was earning revenue
- deposit $180,000 during the peak summer months:
- $100,000 in December
- $80,000 in January
- earn interest on deposited funds
- maintain flexibility to withdraw funds for a new investment opportunity
- ask TMNZ to allocate tax to the correct payment dates once the business’s income tax liability is known.
The results
Emma continued her business growth plans, while she also:
- earned interest on deposits in excess of what her bank was offering
- better matched tax payments to income patterns
- reduced her stress during quieter months
- protected her working capital during winter
- simplified the tax planning process
- created a tax savings discipline for the business
- rested easy knowing no IRD interest or penalties had been incurred.
Going forward, the business can use TMNZ annually as part of growth plans and cashflow strategy.
Your key takeaway
By matching peak periods with future planning, you can earn interest and create a facility to fund business growth when opportunities arise.
For more on how our tax solutions can help your business, go here.
*This scenario is a fictional example created to demonstrate how tax management solutions work to meet unique circumstances in a range of industries.
Managing uncertainty in tax and costs in the construction industry
Working scenario: Wilson Construction.
The situation
James operates a commercial construction company in Hamilton with 45 employees. The company experiences significant variations in monthly income based on project completion milestones. If clients pay late, this further stresses cashflow.
The challenge
For the 2024-25 tax year, Wilson Construction faced:
- uncertain provisional tax obligations due to uncertainty on when income will be earned
- a large variation between estimated profit ($1.8M) and actual profit ($2.9M) when a project was delivered ahead of schedule in the 2025 financial year, rather than the 2026 financial year as expected
- cashflow regularly tied up in materials and labour costs
- Inland Revenue’s prescribed instalment dates that were not aligned with project payment schedules.
The solution
James opted to manage their tax payments through TMNZ because:
- TMNZ allowed flexible payment dates throughout the year
- the company could make 20+ smaller payments instead of 3 large instalments
- they made payments after receiving project milestone payments
- there was no need to estimate their annual tax liability upfront
- they could change payment amounts at any time based on actual cashflow.
The company made 24 payments ranging from $15,000 to $45,000. They timed payments to follow major project milestone payments and adjusted payment sizes based on project profitability. The total tax paid was $812,000.
The results
James enjoyed better cashflow management, as well as:
- reduced stress around provisional tax deadlines
- no Use of Money Interest charges or late payment penalties
- maintaining a strong working capital position
- better aligned tax payments with business income patterns
- avoiding drawing on construction bonds or expensive bank facilities.
Your key takeaway
Using TMNZ solutions, and seasonal financial planning, tax obligations can be managed to align with business and project outcomes, not IRD deadlines.
For more on how our tax finance solutions can help your business, go here.
*This scenario is a fictional example created to demonstrate how tax management solutions work to meet unique circumstances in a range of industries.
Reducing the cost of funds for a dairy farm
Working scenario: Henderson Dairy Farm.
The situation
The Henderson family operates a 650-cow dairy farm in Southland. They recently invested in a new milking shed automation system and expanded their herd, creating irregular cash flow patterns during the upgrade period.
The challenge
In the 2024-25 season, they faced:
- $280,000 investment in automation equipment
- an additional $150,000 for herd expansion
- a provisional tax payment of $165,000 due March 2025
- expected lower income for the next few months, picking up in October
- bank facilities already used for farm improvements
- needing to maintain working capital for winter feed.
The solution
The Henderson’s worked with TMNZ to:
- finance the full $165,000 provisional tax payment
- secure 5.6% interest rate (vs IRD’s 10.88%)
- structure repayment to align with improved monthly income
- use TMNZ’s tax finance solution as an alternative funding source.
The results
The Henderson’s saved approximately $4,950 in interest compared to IRD and bank overdraft rates. They also:
- preserved their working capital for winter feed purchases
- maintained a good standing with existing bank
- protected their new automation investment
- avoided selling stock at suboptimal time
- better aligned provisional tax payments with their income cycle.
Your key takeaway
By creating a long-term plan to address variabilities in cashflow, you can plan ahead and secure lower interest on funds to cover costs.
For more on how our tax solutions can help your business, go here.
*This scenario is a fictional example created to demonstrate how tax management solutions work to meet unique circumstances in a range of industries.
*All interest rates quoted in this article were up to date as at March 2025.
Managing Inland Revenue audits and reassessments
This practical 30-minute session is on using tax pooling to your advantage during Inland Revenue tax audits and reassessments. We’ll show you how being proactive provides the best outcome for you or your clients.
TMNZ has the largest pool of historical tax in New Zealand. We can help with any type of tax – PAYE, FBT, GST, NRWT, terminal tax and provisional tax. Our tax pooling experts are here to support you through audits and voluntary disclosures.
What you’ll learn
- How to reduce interest costs and manage cashflow during a voluntary disclosure
- Effective strategies to manage tax disputes over time
- Q&A.
Who this is for
This webinar is perfect for tax agents, accountants and finance professionals.
This content is for general information purposes only and should not be used as a substitute for consultation with our team of specialists.
The interest rates mentioned in our webinars were accurate at the time of original recording. Please note that Inland Revenue interest rates change over time. Always refer to current official Inland Revenue rates for the most up-to-date information.
Book a tax pooling overview for your business
Is tax pooling the right solution for you? Every business we work with has different needs. Book an overview with one of our tax pooling specialists to find out how we can support you.
Are you in a tight spot with your company tax?
Fibre Cement Solutions Ltd is a family-run business, owned by Rachel Osborn and Graeme Zimmerman, who bring 25 years of construction industry experience with them. As a leading supplier of fibre cement board in New Zealand, they work with several construction partners across the country and after expanding, they have distribution centres in both Auckland and Christchurch.
A few years into business, Rachel, who managed the finances of Fibre Cement Solutions, found herself in a tight spot. It was the middle of COVID-19, and she hadn’t been advised of their upcoming tax liabilities and deadlines. Like many smaller businesses, especially those in the construction industry, the business was experiencing fluctuating cashflow, despite in their case, fantastic growth. As a result, Rachel found herself struggling to pay the unexpected company tax on time, now facing the risk of hefty penalty from Inland Revenue.
Her new accountant suggested she look into tax pooling and made the introduction to Tax Management New Zealand (TMNZ).
And that’s where TMNZ stepped into help.
TMNZ can work directly with any business (or with their accountant) to find a better solution for provisional tax.
Rachel contacted TMNZ to sign up to their Integrated with Inland Revenue service, which gives businesses up to 22 months to pay their company tax without incurring heavy penalties. TMNZ provided Rachel with flexible payment options, charging only a small interest fee for the service, much smaller than IR or bank interest rates. And when her tax payments were made, TMNZ transferred these to IR, as date-stamped payments. Job done.
Rachel’s flexible payment plan with TMNZ allowed her to make payments on dates that suited the business’ cashflow, and payment amounts that worked for her budget. This solution allowed the business to stay compliant with Inland Revenue regulations, avoid fees, and manage tax obligations in a way that better suited the business. Meaning Fibre Cement Solutions could continue to pay staff, meet sales targets and continue to grow.
After her initial positive experience with TMNZ, Rachel now monitors the company’s financial position monthly. She loves the option to pay TMNZ instead of Inland Revenue directly, allowing her to reinvest funds into the business for growth. Rachel says:
“If you are ever in a tight spot re paying your company tax like we were, there is an incredible solution that TMNZ offer… It is so flexible and user friendly and keeps you out of trouble with the IRD!”
“The Team at TMNZ are extremely friendly and can explain tax in layman’s terms which I really loved. I cannot recommend them highly enough”
To learn more about how TMNZ can help your business manage tax payments and gain cashflow flexibility, contact one of our friendly team members here or speak with your accountant about setting up a flexible cashflow arrangement allowing you to choose when you pay your tax.
Reducing risk: 28 October provisional tax
The current market conditions are making it even trickier to work out how much provisional tax to pay, not to mention finding the funds to pay it. That’s why, with 28 October approaching, we’re going to offer some ways to reduce your risk in this uncertain environment.
TMNZ offers options to defer this payment for up to 19 months – without having to worry about any nasty consequence from Inland Revenue (IR). We also look at the pros and cons of the respective options available to calculate your payment.
For taxpayers with a 31 March balance date who file their GST returns every six months, 28 October will be the first of two provisional tax instalments payable for the 2024-25 income year. It is also the first of three instalments payable for those with a 31 May year-end who file their GST returns monthly or every two months. This makes it a major payment date for many businesses in the agricultural sector.
What should you pay?
While working out the liability to the exact cent is far from easy – even at the best of times – it does not change the fact you generally have two options when it comes to calculating your provisional tax payments. They are:
- Pay based on an uplift of an income tax liability from a previous year. This is known as using the standard uplift method.
- Pay based on your current expectation of profitability for the 2024-25 income year.
Paying based on an uplift of a prior year
If you travel down this route, the provisional tax payable for the 2024-25 income year will be based on either:
- Your 2024 income tax liability plus five percent; or
- Your 2023 income tax liability plus 10 percent (if your accountant has not filed your 2024 tax return and does not legally have to do so until 31 March 2025).
The benefit of paying uplift means you will not incur IR interest (UOMI) – from 28 October 2024 if it turns out you have not paid enough provisional tax to satisfy the liability for the year.
Given this is the date which carries the longest exposure to UOMI, sticking with uplift may be a sound insurance policy if you feel a similar result to last year is on the cards or want to play it safe in this uncertain environment to ensure you are not caught short later if business picks up down the track. And besides, if things turn to custard, you can always revise your payment downwards later to account for any overpayment on 28 October once the picture starts to become clearer.
However, the downside of paying on uplift means you may end up making a provisional tax payment that is not reflective of your current earnings (or more than your expected profitability for the year). From a cashflow perspective, that can be problematic as generally you will not be able to get your overpaid tax back from IR until after you have filed your 2024-25 income tax return.
Paying based on forecast profitability
Indeed, there’s no denying many New Zealand businesses have been doing it tough and are forecasting lower profits. As such, you may be considering making a payment on 28 October that is more in line with how you are currently performing – especially if your business earnings have been significantly impacted.
On plus side, you won’t be paying any more provisional tax than you need to if you choose to do this. That will certainly offer a cashflow benefit by allowing you to keep money in your business.
You can always revise payments upward or downward depending on how everything unfolds. However, it means you run the risk of incurring UOMI from 28 October 2024 if you experience a sudden or late upswing in profitability during the backend of the 2024-25 income year and provisional tax paid on this dates turns out to be less than the amount required. That said, there is a way to reduce the interest cost on underpaid tax. More on that shortly.
Do you need to file an estimate with IR to pay less than uplift?
We get this question a lot. You do not need to file an estimate with IRD if you plan on paying provisional tax based on your expected profitability for the 2024-25 income year. There is no legislative requirement to do so. Just make your payment on 28 October as you see fit.
Tax pooling can help if you cannot pay, or it turns out you have not paid enough
No matter the basis you utilise to calculate your 28 October payment, IR-approved TMNZ can offer some assistance, with payment options for taxpayers who:
- Do not or cannot make their payment on the prescribed IR payment date.
- Want to eliminate IR interest and late payment penalties if they underpay their tax.
Pay 28 October provisional tax when it suits you
Where preserving cash is of primary importance, you can use TMNZ to defer an upcoming provisional tax payment for up to 19 months, without facing UOMI and late payment penalties.
TMNZ will make a payment to IR on your behalf on 28 October. You then pay TMNZ later. This can be once the liability for the 2024-25 income year is known or when your cashflow situation improves. The amount owed can also be paid in instalments.
You would have until mid-June 2026 to pay what you owe with Flexitax if you have a 7 April terminal tax date. Check with your accountant if you are unsure what your terminal tax date is. There is some interest to pay to TMNZ – but this is significantly cheaper than IRD’s UOMI rate.
Reduce the cost of underpaid tax
Tax pooling is not just for those who are struggling to pay IR on time.
Where forecasting profitability for the 2024-25 income year is proving challenging or you would simply prefer to make your provisional tax payments based on how your business is performing by reviewing your position at each instalment date, you can rest easy knowing that TMNZ can help in the event you get your payments wrong and wind up with additional tax to pay. That’s because you can use TMNZ to make significant savings on the IR interest cost you face and wipe late payment penalties when you underpay tax.
How? TMNZ lets you apply provisional tax that was originally paid to the tax department on the date(s) it was due against your liability. As such, IR treats it as if you paid on time once it processes this tax pooling transaction. This eliminates any late payment penalties. You have up to 75 days from your terminal tax date for the 2024-25 income year to pay any underpaid provisional tax with TMNZ. It’s a useful option to pull out of your back pocket once you determine your actual position and file your return. The savings TMNZ offers on underpaid tax can be significant.
Speak with your accountant
As always, we recommend you speak with and direct any questions you have about your 28 October provisional tax payment to your accountant. If you don’t have an accountant, check out the directory of firms that TMNZ works alongside. You can filter this list by specialist topic or search for a tax agent in your region.